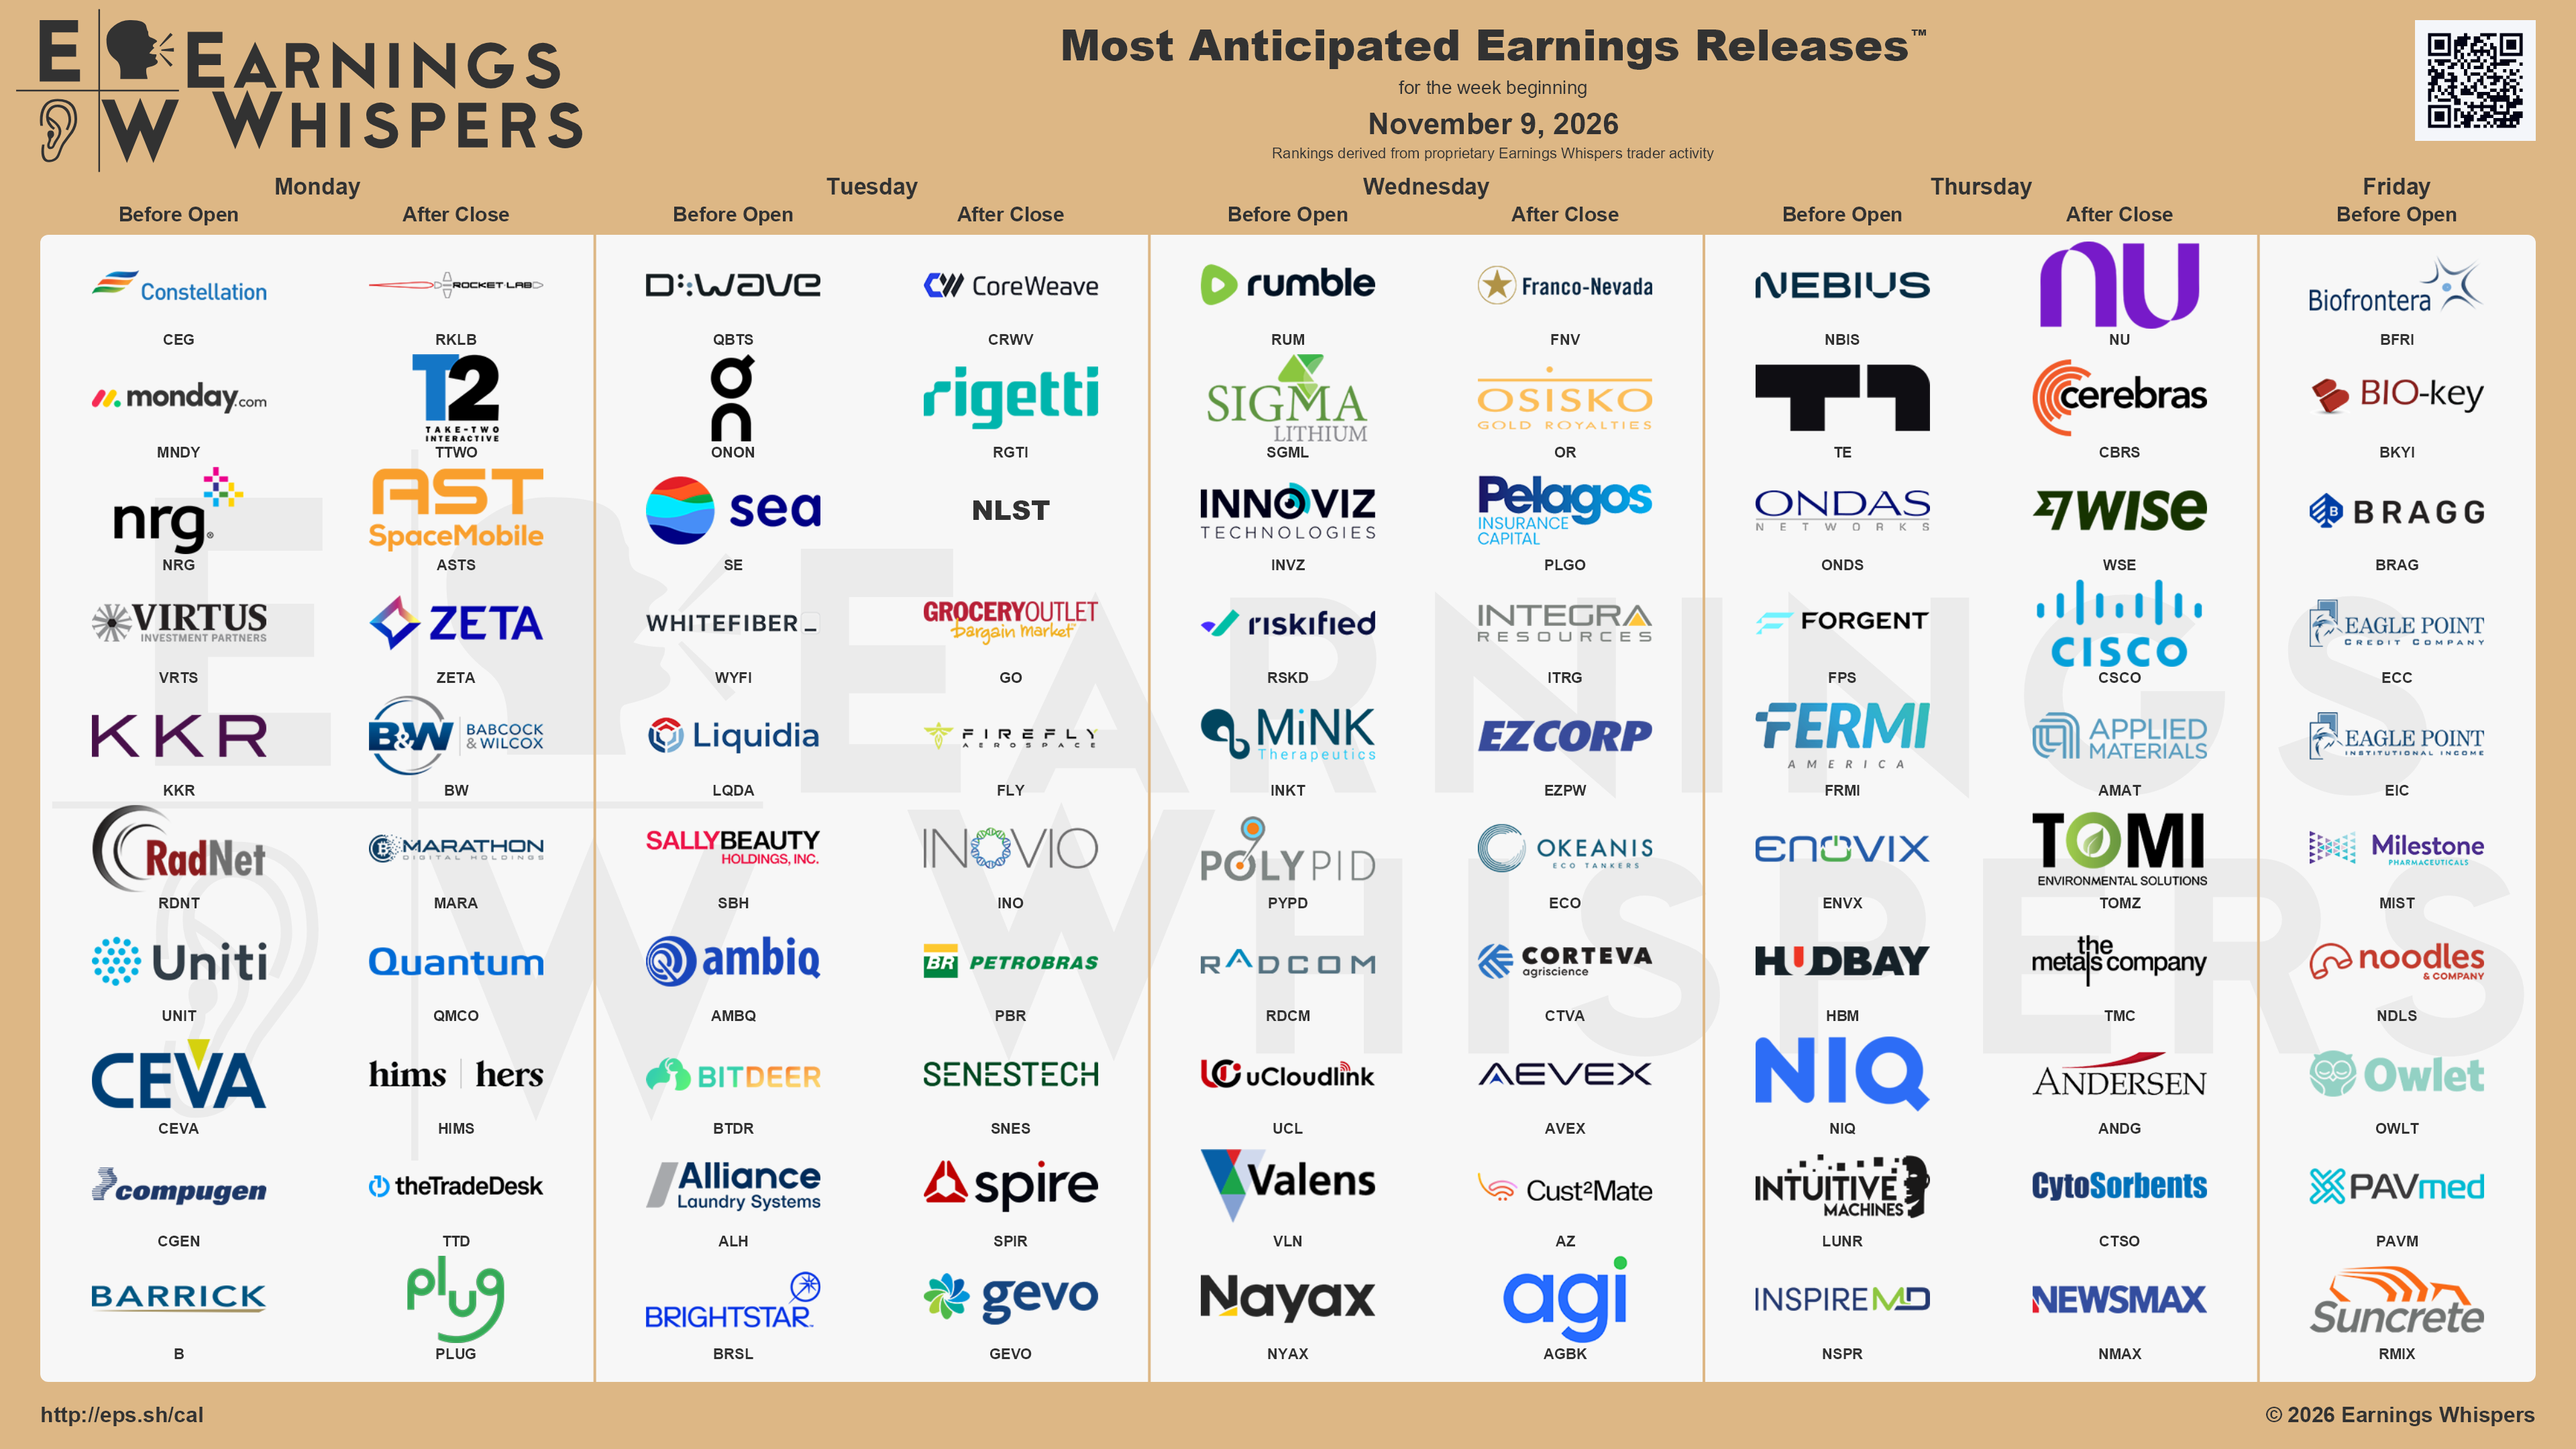
RUM Group Missed Consensus Estimates, Guides In-line
Wednesday, November 11, 2026 at 7:30 AM
RUM Group (RUM) reported a loss of $0.19 per share on revenue of $96.58 million for the third quarter ended September 2026. The consensus estimate was a loss of $0.15 per share on revenue of $89.21 million. The company missed consensus estimates by 26.67% while revenue grew 290.03% on a year-over-year basis.
The company said it expects fourth quarter revenue of $88.0 million to $94.0 million. The current consensus revenue estimate is $92.6 million for the quarter ending December 31, 2026.
Rumble is a high-growth neutral video platform that is creating the rails and independent infrastructure designed to be immune to cancel culture.
The company said it expects fourth quarter revenue of $88.0 million to $94.0 million. The current consensus revenue estimate is $92.6 million for the quarter ending December 31, 2026.
Rumble is a high-growth neutral video platform that is creating the rails and independent infrastructure designed to be immune to cancel culture.