Upcoming Earnings
The Most Anticipated Earnings Releases for the Week of July 20, 2026
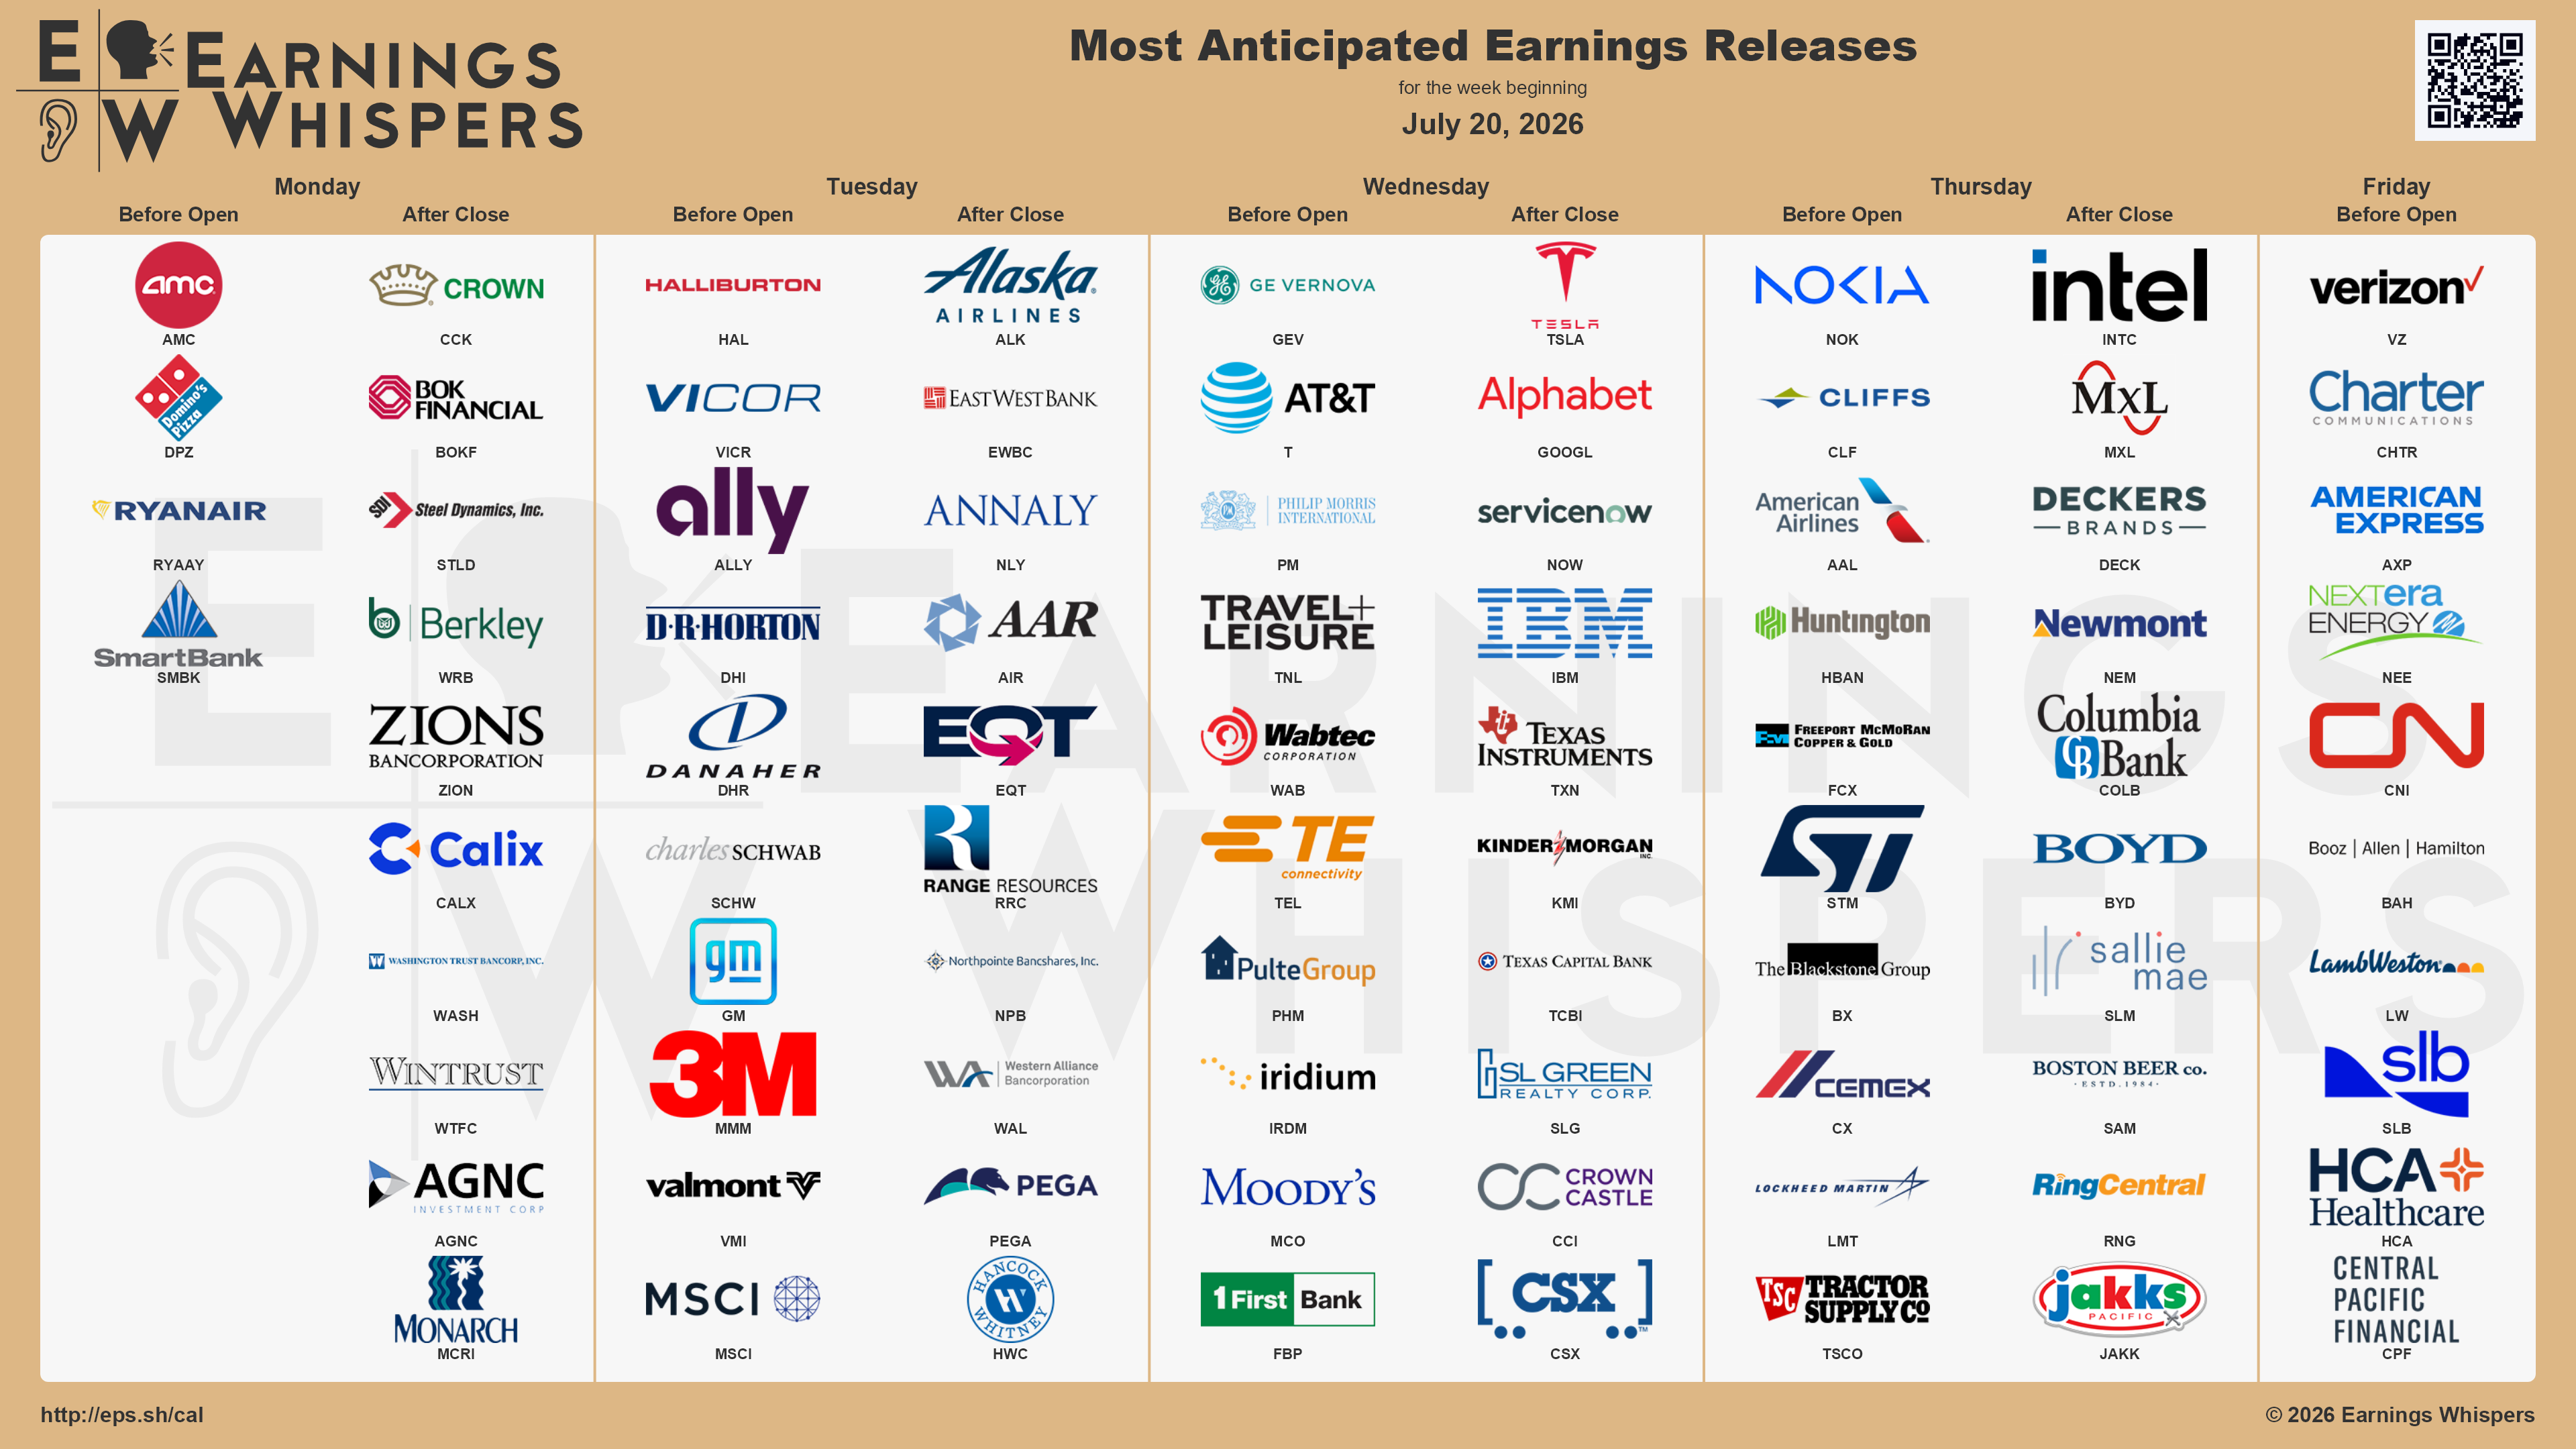
Big Tech, Banks and Bulls: What to Watch as Earnings Season Roars Back to Life
This week's earnings docket reads like a heavyweight fight card, and the smart money is buzzing about the mega-cap names swinging first. Tesla and Alphabet headline a Technology-heavy slate where the mood is decidedly upbeat—both roll into their prints with momentum firmly at their backs and traders leaning bullish, though Alphabet's stock has quietly given back ground since its last report, a wrinkle worth watching before the numbers hit. Intel is the sleeper here: sentiment has swung sharply positive, estimates have been marching higher, and the setup screams turnaround story, but options desks are bracing for one of the wider single-day swings on the board. Don't sleep on the smaller silicon names either—MaxLinear and STMicroelectronics carry some of the strongest under-the-radar optimism, while ServiceNow presents the season's classic head-fake: analysts love the trajectory, yet the tape sentiment is oddly muted, setting up a potential surprise in either direction. Add Texas Instruments and IBM to the mix and Tech alone could set the tone for the entire market.
Beyond the tech gauntlet, the financials form a fascinating undercard as the big banks and insurers open their books. Capital One, American Express, Schwab, Interactive Brokers and regional standouts like Zions and East West Bancorp are drawing genuinely bullish crowds, with steady quarters behind them and expectations trending up—though Western Alliance and W.R. Berkley are the contrarian names flashing caution signs. The industrial and transport complex offers its own drama: United Rentals could deliver fireworks given its outsized expected swing, CSX and Canadian National carry quiet confidence, and the airlines are a coin flip—American and Southwest have room to surprise while Alaska stares down a rough setup. Meanwhile, the market's obvious skeptics are worth circling: Charter, Comcast, Lamb Weston and Domino's all arrive with the wind in their faces, weak sentiment, and stocks that have been drifting lower, making them the potential landmines—or, for the brave, the biggest bounce-back candidates—of the week.
Watch Preview
Nokia's AI/Cloud Inflection Meets High Bar Into Q3
Nokia (NOK) reports Thursday, July 23, 2026 before the open, with the Street looking for $0.07 per share on $5.59 billion in revenue — 8.4% year-over-year growth — while the Earnings Whisper number sits a penny higher at $0.08. Sentiment is decidedly bullish, with 71.1% of investors expecting a beat and estimates revised higher since last quarter. That optimism has a flip side: short interest is up 8.6%, and the stock has drifted 6.1% lower from its post-earnings open, though it still holds 13.4% above its $8.92 200-day moving average. Options traders are bracing for a 13.0% swing versus the 7.0% average move of recent quarters, and on July 14 someone stepped in for 43,045 contracts of the August $12.00 calls.
The setup here is all about follow-through on last quarter's inflection. Management delivered its first hard guidance raise in a year, lifting FY26 network infrastructure growth to 12-14% (from 6-8%) and optical+IP to 18-20%, powered by EUR1bn in new AI & cloud orders at a ~3x book-to-bill and 49% AI/cloud sales growth. Watch for IP networks to finally convert design wins into orders (only +3% last quarter) and for continued gross-margin progress off Q1's 45.5%. Offsetting positives are the deliberate fixed-networks drag (-13%), a flat telecom market, and persistent supply/mix headwinds — 12-18 month optical lead times and memory inflation. With the group profit range reaffirmed rather than raised and a rich implied move, the bar is high; another order acceleration and a formal profit lift would be the catalyst bulls are paying up for.
Tesla's Margin Inflection Meets Its Mega-CapEx Reckoning
Tesla (TSLA) is confirmed to report after the close on Wednesday, July 22, 2026 at approximately 4:05 PM ET. The Street is looking for $0.53 per share on revenue of $25.36 billion (up 12.7% year-over-year), with the Whisper number a touch higher at $0.55. Sentiment leans bullish—58.5% expect a beat—but the setup is more mixed under the surface: short interest has jumped 20.6% since last quarter, overall estimates have been revised lower, and while the stock has drifted 1.5% higher off its last post-earnings open, it still sits 8.7% below its $417.18 200-day moving average. Options are pricing in a 7.1% move versus the 4.3% average of recent quarters, and Friday's tape showed notable buying of 35,552 of the $150.00 puts expiring July 24—worth watching.
The real question is whether the demand and margin inflection can survive scrutiny of the cash story. Q1 delivered a clean sequential ramp in auto gross margin ex-credits (19.2%, up from 15.0% a year ago), a genuine demand resurgence (France/Germany +150% q/q, highest Q1 backlog in over two years), and FSD paid subs climbing to ~1.3M with declining churn—plus newly concrete regulatory wins (Netherlands FSD approval, EU-wide expected Q2, China targeted Q3) and Robotaxi expanding to Dallas and Houston. But Q1's margins leaned on ~$230M of warranty/tariff one-timers, energy's record 39.5% margin got a >$250M one-time tariff boost, and management explicitly guided to negative free cash flow for the rest of 2026 as CapEx escalates past $25B. Watch for margin normalization ex one-timers, the CapEx trajectory, and any hard update on Optimus V3 and China FSD—the operations are improving, but the story has shifted to a cash-consuming, multi-year investment phase.
Intel Rides Momentum Into Q3 as Bulls Pile In and Puts Hedge the Run
Intel (INTC) is confirmed to report earnings on Thursday, July 23, 2026 at approximately 4:00 PM ET. The consensus estimate is $0.21 per share on revenue of $14.42 billion—good for 12.1% year-over-year growth—but the Earnings Whisper number sits meaningfully higher at $0.29, right at management's own guidance range of $13.80B to $14.80B and $0.20 EPS. Sentiment is decidedly bullish, with 82.4% expecting a beat. That optimism has been earned: the stock has drifted 15.6% higher since the last release and now trades 48.4% above its $64.02 200-day moving average. Notably, short interest has still climbed 7.1%, and estimates have been revised higher across the board. Options traders are bracing for a 15.2% swing versus the 9.9% average of recent quarters, and on July 10 we saw notable buying of 21,032 of the $65.00 puts expiring August 28—worth watching as a hedge against this extended run.
The story here has flipped from survival to scaling. Last quarter delivered the sixth straight beat, and a bigger one—revenue $1.4B above midpoint, gross margin at 41% (~650bps ahead of guide), and EPS of $0.29 against a breakeven bar. The catalysts are genuinely new: the TerraFab tie-up with SpaceX/xAI/Tesla, Google as a named multi-year LTA customer, Xeon 6 landing in NVIDIA's DGX Rubin systems, and the accretive Fab 34 buyback. DCAI is accelerating (+22% y/y) and the server CPU outlook was lifted to double-digit unit growth. Watch the offsets: Q2 gross margin was guided down to 39% on early 18A ramp mix, OpEx is likely to top the $16B target, and management flagged 2H PC softness plus rising memory/substrate cost headwinds. With expectations elevated and a large move priced in, execution on margins and the supply ramp is what clears the bar.
GOOGL Q2: Cloud Acceleration Meets the CapEx Question
Alphabet (GOOGL) is confirmed to report Q2 earnings on Wednesday, July 22, 2026 at approximately 4:00 PM ET. The Street sits at $2.87 per share, but the Earnings Whisper number is a full $0.23 higher at $3.10, and sentiment is firmly bullish with 79.6% expecting a beat. That optimism has a counterweight: short interest is up 10.0% since last quarter, and the stock has drifted 7.3% lower from its post-earnings open, though it still holds 7.9% above its $321.27 200-day moving average. Estimates have been revised higher into the print. Options are pricing a 6.8% move versus the 3.8% average of recent quarters, and we flagged notable buying on July 15 of 60,326 of the $415 calls expiring August 21.
The setup is straightforward: last quarter was an across-the-board acceleration, and the question is whether it holds. Cloud is the story - Q1 revenue grew +63% and crossed $20B, margins expanded to 32.9%, and backlog nearly doubled to $462B (though roughly half the jump was new TPU hardware agreements). Search also accelerated for a fourth straight quarter to +19%, and the closed Wiz and Intersect deals add new fuel. The offset is spending: FY26 CapEx was raised to $180-190B, FCF fell to $10.1B on a $35.7B quarterly outlay, and management signaled FY27 will 'significantly increase.' Watch cloud growth sustainability against a shrinking ~1pt FX tailwind, the Wiz margin headwind, and any commentary on whether compute supply constraints are easing.
ServiceNow Q2: AI Momentum Real, But Bears Circle the Organic Raise Question
ServiceNow (NOW) is confirmed to report earnings on Wednesday, July 22, 2026 at approximately 4:10 PM ET. The consensus estimate sits at $0.86 per share on revenue of $3.92 billion (21.9% YoY growth), with the Earnings Whisper number a touch higher at $0.90. Guidance was for revenue of roughly $3.82 billion. Sentiment is bearish heading in, though 69.0% still expect a beat. Short interest has more than doubled (up 107.9%) since last report, yet the stock has drifted 18.3% higher off its post-earnings open to sit 20.0% below its $129.10 200-day moving average. Estimates have been revised lower. Options traders are pricing a 12.8% move versus the 10.2% recent average, and we flagged notable buying of 15,010 of the $60.00 puts (expiring July 24) on July 16.
The setup mirrors last quarter's tension: fundamentals are genuinely improving, but the market wants proof it's organic. AI monetization is the standout, with NowAssist run-rate disclosed at $1.5B versus the prior $1B FY26 target, million-plus NowAssist customers up over 130% YoY, and record new-logo lands. The offsets are what have bears leaning in — Q1's raise was almost entirely Armis-driven, the organic full-year guide was held flat, and margins stepped down across the board (op margin to 31.5%, FCF to 35%) on integration costs, with Q2 op margin guided to just 26.5%. Watch for whether management raises the organic revenue outlook and provides cleaner inorganic contribution detail; also monitor the ~75bp Middle East on-prem timing headwind flagged as a Q2 risk. A clean organic raise is the swing factor for the stock.
AMC: Box-Office Recovery Finally Real — Arena One Adds a New Leg
Logo for AMC Entertainment Holdings, Inc
AMC Entertainment (AMC) is confirmed to report earnings Monday, July 20, 2026 at approximately 7:40 AM ET. Consensus calls for breakeven results on revenue of $1.48 billion — 5.9% year-over-year growth — while the Earnings Whisper number sits at $0.03 per share. Sentiment is decidedly bullish, with 76.2% expecting a beat, and the setup backs it up: short interest has collapsed 40.9% since last quarter, the stock has drifted 16.2% higher off its post-earnings open to trade 6.4% above its $1.82 200-day moving average, and overall estimates have been revised higher. Options traders are pricing in a hefty 34.3% move versus a recent-quarter average of just 2.6%, and Friday, July 17 brought notable buying of 16,440 of the $1.50 puts expiring August 21 — worth watching as a hedge against that outsized implied swing.
The story into this print is a box-office recovery that has finally shown up in the numbers. Last quarter delivered the best Q1 adjusted EBITDA since 2019 ($38.3M, a $96M YoY swing), revenue back above $1B for the first time since 2019, and a record $15.19 contribution margin per patron on +22% North American box office. The balance sheet is materially de-risked — notes converting to equity, 2027 debt refinanced cheaper to 2031, and labor peace signed. The new catalyst is Arena One, a live-concert product rolling out across 300+ US theaters at near-zero upfront capex, alongside firm 45-day theatrical windows from Universal and Paramount. Watch the seasonal cash draw (cash fell to $339M) and whether management moves off its reaffirmed full-year box-office guide toward the raised top end — AMC is still not full-year free-cash-flow positive and needs the 2026/2027 slate to deliver.
IBM: Improving Fundamentals Meet a Beaten-Down Stock and Rising Skepticism
Logo for International Business Machines Corp.
IBM is confirmed to report earnings on Wednesday, July 22, 2026 at approximately 4:10 PM ET, with the Street looking for $3.00 per share on $17.59 billion in revenue—3.6% year-over-year growth—while the Earnings Whisper number sits slightly below at $2.93. Sentiment is split: 54.2% of investors expect a beat and overall estimates have been revised higher since last quarter, yet the setup is anything but clean. Short interest has surged 47.2% since the last release, and the stock has drifted 8.4% lower from its post-earnings open to trade 22.4% below its 200-day moving average of $273.99. Option traders are bracing for a 7.1% move, in line with the 6.9% average of recent quarters, and we noted bearish positioning on July 14 with 4,373 contracts of the $200.00 puts (Aug 21 expiry) bought.
The real story is the disconnect between an improving business and a punished stock. Last quarter delivered a clean across-the-board beat—record Q1 free cash flow of $2.2B (+13%), 140bps of margin expansion, and raised guides for software (10%+) and data (low-20%+) after Confluent closed roughly two months early. Red Hat reaccelerated to 10% and consulting signings returned to growth (+6%) after a prolonged slump. The key watch item: management deliberately held the full-year revenue and FCF guide despite the strong start, citing macro uncertainty. Watch for whether a second consecutive strong quarter finally prompts a raise—and monitor the offsets management flagged: Q2 margin expansion guided to just ~50bps on Confluent dilution (~$600M), infrastructure guided down low-single-digits, and DRAM supply chain dislocation pressuring RHEL-linked hardware.
GEV Into Q2: Momentum Broadens as Power and Electrification Accelerate
GE Vernova (GEV) is confirmed to report earnings on Wednesday, July 22, 2026 at approximately 6:30 AM ET. The consensus earnings estimate is $3.16 per share on revenue of $10.77 billion, representing 18.2% year-over-year revenue growth, and the Earnings Whisper number is $3.47 per share — a healthy 31-cent cushion that reflects how the buy-side is positioned. Investors are bullish going in, with 69.6% expecting a beat, and overall earnings estimates have been revised higher since last quarter. Notably, though, short interest has jumped 60.3% even as the stock sits 29.6% above its $816.14 200-day moving average, a tension worth watching. Option traders are pricing in a 10.9% move versus the 6.4% average of recent quarters, and on Thursday, July 16 there was notable buying of 1,677 of the $840.00 puts expiring September 18, 2026 — some hedging of that stretched positioning.
The setup is defined by last quarter's broad guidance raise, and the question is whether it continues. Management lifted FY26 revenue to $44.5-45.5B, adjusted EBITDA margin to 12-14%, and FCF sharply to $6.5-7.5B, with $4.8B of FCF in Q1 alone — more than all of FY25. Backlog climbed to $163B and the $200B target was pulled forward to 2027; gas under contract hit 100GW with pricing 10-20 points higher per kW, and electrification orders rose 86% with ~$2.4B of data center orders exceeding all of FY25. Prolec is now consolidating accretively at >20% margins. The lone soft spot remains wind (Q1 revenue -25%, ~$400M FY26 loss) and the $250-350M tariff impact, but both are contained and previously flagged. Watch for another power/electrification order print and any move on the FCF guide — the bar is high, but so is the trajectory.
Domino's Faces the Consumer: Can Q2 Halt the Comp Slide?
Domino's Pizza (DPZ) is confirmed to report earnings on Monday, July 20, 2026 at approximately 6:05 AM ET. The consensus earnings estimate is $4.11 per share on revenue of $1.18 billion, representing 3.0% year-over-year revenue growth, and the Earnings Whisper number is $3.98 per share — a rare below-consensus whisper that speaks to the caution setting in. Investors are bearish heading into the print, with just 44.4% expecting a beat. Short interest has climbed 13.2% since last quarter, and the stock has drifted 5.6% lower from its post-earnings open to sit 14.5% below its 200-day moving average of $376.86, with estimates broadly revised lower. Option traders are pricing a 7.0% move versus a 3.3% average in recent quarters, though notable buying of 909 of the $360 calls expiring August 21 on Friday hints at some contrarian positioning.
The overhang here is simple: last quarter marked a clear negative inflection. US comps decelerated to +0.9% from +3.7%, delivery turned negative, international slipped to -0.4%, and management cut guidance on every line — US comp, international, global retail sales, and operating income growth — while flagging a consumer at COVID-level sentiment lows and intensifying competition on value. The bull case (roughly 450 announced competitor closures, ongoing store growth, stepped-up buybacks with ~$1.29B remaining, and back-half pizza innovation) remains intact but is now largely back-half and long-term dependent. Watch US same-store sales and whether the March weakness carried into Q2; anything confirming stabilization is the swing factor for a stock priced for disappointment.
TXN: Broad-Based Acceleration Meets a Sky-High Bar
Texas Instruments (TXN) reports Wednesday, July 22, 2026, after the close (~4:00 PM ET). Consensus sits at $1.91 EPS on $5.22B in revenue—17.4% YoY growth—while the Earnings Whisper number is a full dime higher at $2.01. Management guided $1.77–$2.05 EPS on $5.00B–$5.40B. Sentiment is decidedly bullish: 81.3% expect a beat, short interest has fallen 5.0% since last quarter, estimates have been revised higher, and the stock has drifted up 9.1% post-earnings to trade 28.4% above its $221.24 200-day average. Options are pricing an 11.6% move (vs. a 10.4% recent average), and we flagged notable buying of 7,144 of the $400 calls (exp. 7/31) on July 9.
The setup here is momentum meeting a high bar. Last quarter was a genuine beat-and-raise inflection—Q1 revenue of $4.8B (+9% QoQ, +19% YoY), gross margin up 210bps to 58%, flat pricing (better than the ~2-3% decline modeled), and above-seasonal Q2 guidance. Industrial (+30%+ YoY), data center (~90% YoY), and comms all accelerated, and FCF/share of $8 for 2026 is now 'highly probable.' The two things to watch: management's own caution on 2H sustainability after 2025's 'false start,' and continued softness in automotive (mid-single YoY, China down sequentially). With sentiment and the stock this stretched, the guide—not the print—is what matters.